True All-In Costs for Buying a 4-to-8 Unit Property in North Park San Diego
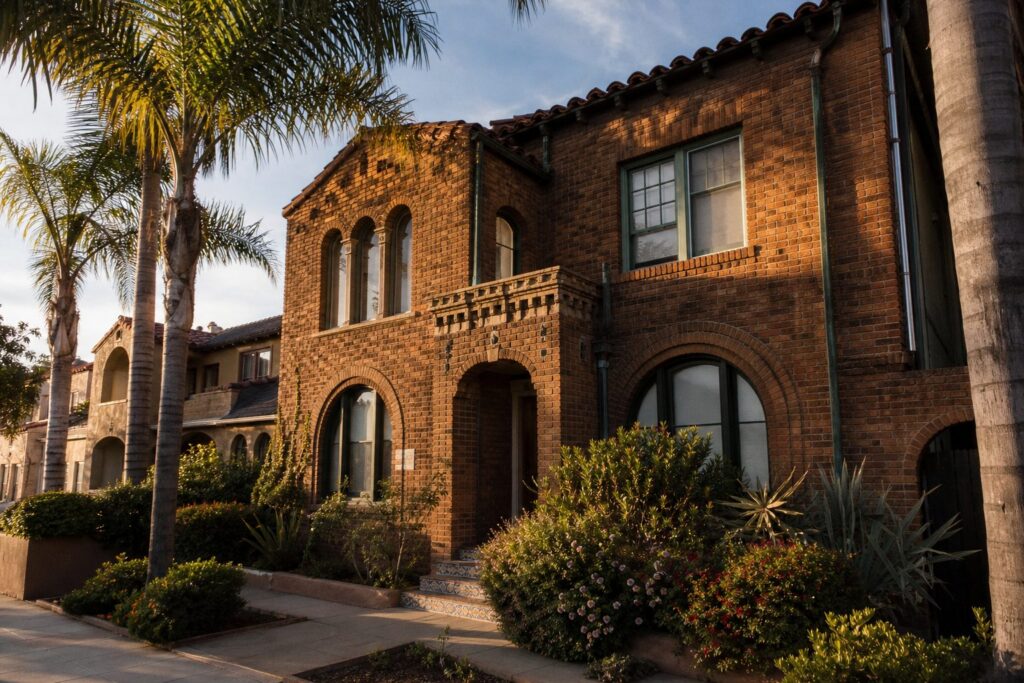
What are the true all-in acquisition costs for buying a 4-to-8 unit multifamily property in North Park, San Diego, in 2026, including due diligence, lender fees, and reserves a bank won’t tell you about?
Your true all-in cost on a North Park multifamily acquisition typically runs 8% to 14% above the purchase price once you factor in lender fees, due diligence, closing costs, and the reserves no bank will volunteer to explain upfront.
Why This Matters Right Now in San Diego’s Multifamily Market
If you’re underwriting a 4-to-8 unit building along the 30th Street corridor or near University Avenue in North Park, you already know the sticker price is only part of the story. What catches most investors off guard is the gap between the contract price and the actual check they need to write.
North Park sits in ZIP 92104, one of San Diego’s most renter-dense neighborhoods at roughly 71% renter-occupied. Average rents hit $2,758 per month in 2026, up 1.63% year over year. Class B and C vacancy rates countywide are sitting at just 3.3%, well below the 6.4% at Class A properties. That kind of demand is what draws investors here. But if you undercapitalize on the front end, those strong fundamentals won’t save you.
Having closed over 275 transactions across San Diego County over 16 years, I’ve walked investors through this exact math dozens of times. Here’s how to get it right.
What North Park 4-to-8 Unit Properties Actually Cost in 2026
Before we layer in hidden costs, you need a realistic purchase price baseline. County-wide average price per unit for multifamily is $362,097. For Class B properties in core neighborhoods like North Park, that number jumps above $500,000 per unit according to Q2 2026 market data.
Here’s what that looks like in practice:
- 4 units in North Park: Expect a purchase price between $1.4M and $2.0M, depending on condition, unit mix, and proximity to the 30th and Upas corridor
- 6 units in North Park: Typically $2.1M to $3.0M
- 8 units in North Park: Can range from $2.9M to $4.0M or higher, especially if the property has ADU potential or has been partially renovated
One investor I worked with last year was targeting a 6-unit building near El Cajon Boulevard and 30th Street. His initial budget was $2.4M for the purchase. By the time we mapped out every cost layer below, his true all-in number was closer to $2.72M. That $320,000 gap is what this guide is about.
Lender Fees in North Park: The 5-Unit Threshold Changes Everything
Here’s something your lender may not emphasize. The moment you cross from 4 units to 5 units, your financing shifts from residential to commercial. That single extra unit changes your entire cost structure.
Residential Financing (4 Units)
- Loan origination fee: 0.5% to 1.0% of the loan amount
- Appraisal: $500 to $800 for a standard residential appraisal
- Rate environment: 30-year fixed is available, with rates currently in the mid-6% range per Freddie Mac data (6.48% as of June 2026)
- San Diego County conforming limit: $1,104,000 for a single-family unit, with higher limits for 2-to-4 unit properties
Commercial Financing (5-to-8 Units)
- Loan origination fee: 1.0% to 2.0% of the loan amount. On a $2M loan, that’s $20,000 to $40,000
- Commercial appraisal: $3,500 to $7,500 using the income approach, not comparable sales
- Rate premium: Expect 1.0% to 2.5% above conforming rates
- Loan term: Typically a 5-to-10 year term with 25-to-30 year amortization, meaning you’ll face a balloon payment or refinance event
What does that actually mean for your wallet? On a $2.5M acquisition with 25% down, a 1.5% origination fee on a $1.875M loan is $28,125. Add the commercial appraisal and you’re already $35,000 into lender costs before you’ve touched a single inspection.
Some investors are currently choosing shorter 3-to-5 year loan terms to manage rate uncertainty, which can reduce rate premiums but compresses your refinance timeline. I always walk my clients through both scenarios so the decision is clear, not cloudy. A cloudy mind can’t make decisions.
Due Diligence Costs That Don’t Show Up on a Closing Disclosure
Your lender’s good faith estimate will show the appraisal, title, and maybe a basic inspection. It will not show the due diligence you actually need to protect yourself on a North Park multifamily property built between 1905 and 1940, which is exactly when most of the housing stock in the Burlingame and Dryden Historic Districts was constructed.
Here’s what I tell my clients to budget:
- Property inspection (multi-unit): $1,200 to $2,500 depending on unit count and building age
- Sewer lateral scope: $300 to $500 per lateral. On a property with older clay pipes near Myrtle Avenue, this is non-negotiable
- Pest/termite inspection: $200 to $400, though treatment can run $2,000 to $8,000 on older wood-frame buildings
- Roof inspection: $300 to $600. Many North Park buildings have flat roofs with deferred maintenance
- Phase 1 environmental assessment: $2,000 to $4,000, often required by commercial lenders for 5+ unit properties
- Rent roll and lease audit (attorney review): $1,500 to $3,000 to verify existing leases, tenant rights under San Diego’s Residential Tenant Protection Ordinance, and AB 1482 compliance
- Zoning and permit review: $500 to $1,500, especially important given that the City of San Diego issued over 500 development permits in the North Park community planning area over the past 12 months
Total due diligence budget for a 4-to-8 unit North Park property: $6,000 to $15,000, depending on building condition and unit count.
One couple I represented was evaluating a 5-unit property just south of University Avenue. The seller’s disclosures looked clean. But the sewer scope revealed a collapsed lateral that would cost $12,000 to replace. We renegotiated an $11,000 credit at close. Without that $400 scope, they would have inherited that problem on day one.
The Reserves Your Bank Won’t Mention in San Diego
Banks care about one thing: whether you can make the monthly payment. They do not care whether you can survive your first HVAC failure, a vacancy event, or a tenant turnover that requires a full unit rehab. That’s on you.
Here’s what I recommend investors set aside before closing on a North Park multifamily:
- Operating reserves (minimum 3 months of PITI plus operating expenses): On a $2M property with $14,000/month total obligations, that’s roughly $42,000
- Capital expenditure reserve: 3% to 5% of the purchase price. For a $2M building, that’s $60,000 to $100,000 set aside for roof, plumbing, electrical, or unit renovations
- Vacancy reserve: Even with North Park’s tight 3.3% Class B/C vacancy rate, budget 5% of gross rents annually. With average two-bedroom rents at $3,729, that adds up quickly across multiple units
- Tenant turnover costs: $3,000 to $8,000 per unit for cleaning, paint, flooring, and marketing. Budget for at least one turnover per year in your first 24 months
What I’ve seen repeatedly after 16 years and 275 closings in San Diego is that investors who skip reserves end up selling within 3 years, usually at a loss, because one unexpected expense forces a cash crunch. Strong reserves are what separate long-term wealth builders from short-term headaches.
Closing Costs and Transfer Fees Specific to North Park San Diego
Beyond lender fees and reserves, your standard closing costs on a multifamily acquisition in San Diego County include:
- Title insurance (owner’s policy): $3,000 to $6,000 depending on purchase price
- Escrow fees: Typically split between buyer and seller, your half runs $2,000 to $4,000
- County recording fees: $75 to $225
- Documentary transfer tax: $1.10 per $1,000 of the purchase price. On a $2M property, that’s $2,200
- Property tax proration: Calculated at approximately 1.1% to 1.25% of the purchase price annually, prorated to your closing date
- Insurance (first year premium for landlord/commercial policy): $3,000 to $8,000 depending on coverage level, building age, and unit count
- Mills Act consideration: If your North Park property falls within the Burlingame or Dryden Historic Districts, you may qualify for Mills Act property tax savings of 40% to 60%, which significantly changes your long-term operating costs
Total closing costs typically run 2% to 3.5% of the purchase price.
Building Your True All-In Number for North Park in 2026
Let me put this all together with a realistic example. Say you’re acquiring a 6-unit building in North Park for $2.5M:
- Down payment (25%): $625,000
- Loan origination (1.5%): $28,125
- Commercial appraisal: $5,500
- Due diligence (inspections, scopes, attorney review): $10,000
- Closing costs (title, escrow, transfer tax, recording): $15,000
- First-year insurance: $6,000
- Operating reserves (3 months): $42,000
- CapEx reserve: $75,000
Total cash needed at or near closing: approximately $806,625
That’s 32% of the purchase price in cash or liquid assets. Not 25%. Not “just the down payment.” Thirty-two percent. And that’s before any day-one deferred maintenance surprises.
Frequently Asked Questions
How much cash do I really need to buy a 5-unit building in North Park?
Plan for 30% to 35% of the purchase price in total liquid capital. This covers your down payment (typically 25% on commercial), lender fees, due diligence, closing costs, and at least three months of operating reserves. On a $2M property, you’re looking at roughly $600,000 to $700,000 in available funds before accounting for capital expenditure reserves.
Why do lender costs jump at 5 units in San Diego?
Properties with five or more units require commercial financing rather than residential. This means higher origination fees (1% to 2% vs. 0.5% to 1%), commercial appraisals costing $3,500 to $7,500, shorter loan terms with balloon payments, and rate premiums 1% to 2.5% above conforming residential rates. The underwriting process is entirely different.
What due diligence inspections should I get on a North Park multifamily property?
At minimum, you need a full property inspection, sewer lateral scope (critical for pre-1940 buildings), pest and termite report, roof inspection, and a lease and rent roll audit by a real estate attorney. For 5+ unit properties, commercial lenders often require a Phase 1 environmental assessment as well, adding $2,000 to $4,000 to your costs.
What are typical cap rates for 4-to-8 unit properties in North Park right now?
San Diego multifamily cap rates have stabilized near 4.8% to 4.9% countywide. In a core walkable neighborhood like North Park with a Walk Score of 86 and Class B/C vacancy rates at 3.3%, well-maintained smaller properties may trade at mid-5% cap rates, reflecting the strong renter demand and limited supply.
How much should I budget for reserves on a San Diego multifamily property?
I recommend three months of total obligations (mortgage, taxes, insurance, and operating expenses) as operating reserves, plus 3% to 5% of the purchase price as a capital expenditure reserve. On a $2M North Park building, that’s roughly $42,000 in operating reserves and $60,000 to $100,000 in CapEx reserves.
Are there property tax savings available in North Park?
Yes. Properties in the Burlingame and Dryden Historic Districts may qualify for Mills Act contracts, which can reduce property taxes by 40% to 60%. This is a significant long-term benefit that can improve your cash-on-cash returns materially. The application process requires commitment to maintaining the historic character of the building.
What are North Park rents for multifamily units in 2026?
Average rent in North Park is $2,758 per month as of 2026, up 1.63% year over year. Studios average $2,369, one-bedrooms average $2,548, and two-bedrooms average $3,729. These rents sit roughly 29% above the national average, reflecting the neighborhood’s walkability and lifestyle appeal.
Can I add ADUs to a North Park multifamily building?
Yes. Under San Diego’s current ADU regulations, existing multifamily structures can add up to eight detached ADUs, as long as the number of new ADUs does not exceed the number of existing units. Non-livable spaces within the building can also be converted to ADUs, up to 25% of the existing unit count.
What tenant protections apply to North Park multifamily properties?
San Diego’s Residential Tenant Protection Ordinance provides just-cause protections from day one of tenancy, which is more restrictive than state AB 1482 rules that apply after 12 months. You need a real estate attorney reviewing your lease structures before close, not after. Budget $1,500 to $3,000 for this review.
How long does it take to close on a 5-to-8 unit property in San Diego?
Commercial multifamily closings typically take 45 to 60 days, longer than the 30-day standard for residential transactions. The extended timeline reflects the commercial appraisal process, additional lender underwriting requirements, and the more involved due diligence period for income-producing properties.
The Bottom Line
Buying a 4-to-8 unit multifamily property in North Park is one of the strongest long-term investment moves you can make in San Diego. The neighborhood’s 71% renter occupancy, tight Class B/C vacancy at 3.3%, and rents 29% above the national average create a compelling income story. But walking in without a clear picture of your true all-in costs is how investors get into trouble.
Your real number is not the purchase price. It’s not the purchase price plus down payment. It’s every dollar mapped out in this guide, totaled honestly, with reserves that let you sleep at night.
Understanding all the costs involved in buying a home is essential for any real estate investor. If you’re evaluating a North Park multifamily deal and want a clear-eyed walkthrough of the numbers, I’m here to help. With 180 five-star reviews, 275 closed transactions, and 16 years in San Diego real estate, I bring the kind of experience that keeps investors from learning expensive lessons the hard way. Reach me at 858-405-0002, Scott Cheng, Broker Associate with REAL Brokerage, DRE# 01509668.